
Borrowing allows you to fund an immediate capital requirement today and repay it over time alongside interest and agreed administrative charges. However, not all loan products function the same way: some require physical collateral (secured loans), while others do not (unsecured loans); some disburse funds strictly for designated purposes (such as home or education loans), while others operate as flexible revolving credit lines. Here, we examine nine common retail and commercial lending products in India.
1. Credit Card
A credit card is a revolving unsecured credit facility that allows you to make purchases and pay for services up to a pre-approved credit limit set by the card issuer. At the end of each monthly billing cycle, you receive a statement. If you settle the "Total Amount Due" in full on or before the payment due date, retail purchases enjoy an interest-free grace period (typically 20 to 50 days, depending on transaction timing and issuer terms).
Paying only the "Minimum Amount Due" (MAD) does not clear your liability—it merely avoids late payment charges while the revolving balance attracts steep finance charges (typically 36% to 45% APR) plus GST. Cash withdrawals from ATMs (cash advances) attract immediate interest from day one alongside transaction fees, with no grace period. Scrutinize joining/annual fees, APR, interest-free periods, reward terms, late fees, and over-limit charges. Never treat a credit card as supplemental income or an inexpensive substitute for long-term borrowing.
Estimate how long it will take to clear your outstanding debt and calculate the cumulative interest cost using our Credit Card Payoff Calculator.
2. Home Loan
A home loan is a secured long-term credit facility provided by banks and Housing Finance Companies (HFCs) to purchase, construct, extend, or renovate residential property. The underlying property is mortgaged to the lender as primary collateral until the loan is fully repaid. Repayment occurs via Equated Monthly Installments (EMIs) comprising principal and interest components.
Clarify whether the interest rate is fixed or floating (typically linked to the RBI Repo Rate via an External Benchmark Lending Rate / EBLR). When floating rates adjust, understand whether your monthly EMI increases or the loan tenure is lengthened. Review upfront processing charges, legal and technical valuation fees, stamp duty, margin money requirements (down payment), and part-prepayment or foreclosure rules (RBI prohibits foreclosure penalties on floating-rate individual home loans).
Project your monthly installment, interest component, and the interest-saving impact of part-prepayments using our Home Loan EMI Calculator.
3. Car and Vehicle Loan
A vehicle loan provides financing to purchase a new or pre-owned car or two-wheeler. EMIs are computed based on the financed loan amount, down payment, interest rate, and tenure (typically 3 to 7 years). The vehicle is legally hypothecated to the lender on its registration certificate (RC) until all EMIs are cleared; upon final repayment, obtain a No Objection Certificate (NOC) from the lender to remove the hypothecation endorsement at the Regional Transport Office (RTO).
Compare the on-road price, required down payment, processing fees, interest computation method (reducing balance vs. flat rate), prepayment charges, and insurance costs. Note that comprehensive motor insurance and loan financing are separate financial products—you are legally entitled to purchase compliant vehicle insurance independently from any IRDAI-registered insurer rather than being forced to buy the dealer's in-house package.
Evaluate different combinations of down payment, interest rates, and loan tenures using our Car Loan EMI Calculator.
4. Education Loan
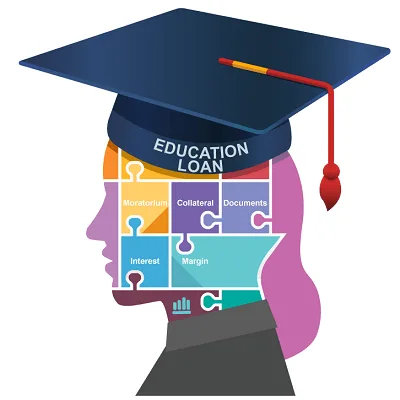
An education loan finances tuition fees, hostel/living expenses, books, and essential study equipment for higher education or professional degree programs in India or abroad. Eligibility, institutional accreditation, loan limits, co-borrower requirements (usually parents or spouse), collateral requirements, and interest rates depend on the lender and scheme guidelines.
Clarify how interest is calculated during the study tenure and moratorium period (typically course duration plus 6 to 12 months after graduation), whether servicing simple interest during the moratorium earns an interest concession, and whether unpaid interest is capitalized (added to the principal). Review co-borrower legal liability, collateral coverage for loans above ₹7.5 lakh, and the financial implications of changing courses or pausing studies.
Simulate moratorium interest accrual, capitalization, and monthly repayment EMIs using our Education Loan Calculator.
PM-Vidyalaxmi Scheme
PM-Vidyalaxmi is a Central Government initiative providing a unified portal for education loan applications and interest subvention for students admitted to Quality Higher Educational Institutions (QHEIs). First, access the official PM-Vidyalaxmi portal and review the "NEW LIST OF PM VIDYALAXMI INSTITUTES" to verify whether your institution is recognized under the current QHEI list (based on NIRF rankings and accreditation).
Key Features under Scheme Guidelines:
- Collateral-Free & Guarantor-Free Loans: Eligible students admitted to QHEIs can apply for collateral-free, third-party-guarantor-free education loans. The Government of India provides lenders a 75% credit guarantee for loans up to ₹7.5 lakh; this credit guarantee is for the lending bank and is not a loan waiver for the student borrower.
- 3% Interest Subvention: Eligible students from families with an annual income of up to ₹8 lakh who are not receiving benefits under other government scholarship or subsidy programs may receive a 3% interest subvention on education loans up to ₹10 lakh during the moratorium period (capped at 1 lakh new eligible beneficiaries annually). This subsidy is subject to program quotas and priority criteria; remaining interest and the entire principal must be repaid as contracted.
- Comparison with CSIS: Students with an annual family income up to ₹4.5 lakh may qualify for full moratorium interest subsidy under the Central Sector Interest Subsidy Scheme (CSIS). This is distinct from PM-Vidyalaxmi's 3% subvention. Per PM-Vidyalaxmi FAQs, admissions secured through management quotas are not eligible.
Before applying, consult the Ministry of Education scheme guidelines alongside the official portal's QHEI list, documentation requirements, and application status trackers.
5. Personal Loan
A personal loan is an unsecured credit facility disbursed without requiring physical collateral. It can be used for diverse personal requirements—such as medical emergencies, weddings, home improvements, or unexpected travel—though lenders restrict its deployment in speculative activities like stock market trading or crypto purchases. Eligibility and interest rates depend heavily on monthly income, employer category, credit score (CIBIL/Experian), and existing Debt-to-Income (DTI) obligations.
Because it is unsecured, personal loan interest rates are noticeably higher (typically 10.5% to 24% p.a.) than secured loans. Compare the effective interest rate, upfront processing fees (1% to 3% plus GST), penal charges, foreclosure lock-in periods, and the total cost of credit before committing.
Estimate your EMI, cumulative interest outlay, and net disbursement after processing fees using our Personal Loan EMI Calculator.
6. Gold Loan
A gold loan is a secured loan obtained by pledging physical gold jewelry or recognized gold coins with a bank or Non-Banking Financial Company (NBFC). The lender assesses the karat purity and net weight of the gold (excluding stones) to determine the loan amount, subject to RBI's regulatory Loan-to-Value (LTV) ceiling (typically up to 75% of the gold's appraised value). Pledged ornaments remain safely deposited in the lender's vault until the loan is fully closed.
Ensure you receive a written appraisal receipt detailing gross weight, net gold weight, purity, interest rate, repayment frequency (e.g., monthly EMI, bullet repayment at maturity, or interest servicing with principal at term-end), and loan tenure. If the borrower defaults or fails to renew/repay, the lender has the legal right to auction the pledged gold after serving statutory notices to recover the outstanding balance.
7. Career and Business Loans
The term "Career Loan" is not a standardized product across Indian financial institutions. If intended for upskilling, executive certifications, or vocational training, it is typically processed as an education or skill-development loan. If intended to establish, capitalize, or expand a venture, it falls under business or Micro, Small, and Medium Enterprise (MSME) financing.
Business loan evaluations examine business plans, audited cash flows, bank turnover, Goods and Services Tax (GST) filings, credit history, and available collateral or CGTMSE credit guarantee coverage. Never assume automated eligibility based solely on the marketing of government-sponsored schemes (such as PMMY Mudra or Stand-Up India); always verify current eligibility criteria, interest rates, collateral terms, processing charges, and documentation with the lending bank.
8. Agricultural Loan
Agricultural credit encompasses diverse financing facilities designed for farming and allied activities—including seasonal crop cultivation, purchase of seeds/fertilizers, irrigation setups, dairy/livestock farming, agricultural machinery, and farm infrastructure development. Short-term crop loans and long-term farm mechanization loans feature distinctly different tenures and repayment cycles.
Repayment schedules are typically aligned with agricultural harvest cycles and seasonal crop cash flows. Under the Kisan Credit Card (KCC) scheme, eligible farmers receive a revolving credit line with subsidized interest rates and timely repayment incentives (Modified Interest Subvention Scheme / MISS). Review land holding verification, hypothecation of crops or machinery, annual card renewal requirements, and tenure conditions directly with the issuing rural or commercial bank.
9. Loan Against Securities (Mutual Funds and Shares)
A Loan Against Securities (LAS / LAMF) allows investors to pledge eligible mutual fund units, equity shares, or government bonds through a depository (CDSL/NSDL) to secure an overdraft limit or term loan without selling their portfolio. This unlocks short-term liquidity while preserving ownership, dividend entitlements, and long-term compounding.
Key Considerations:
- Loan-to-Value (LTV) Margins: Regulatory and institutional LTV ratios typically range from 50% for equity shares and equity mutual funds to 70%–80% for debt funds and government securities. Not every stock or fund scheme is on the lender's approved collateral list.
- Margin Calls & Liquidation Risk: Because market prices fluctuate continuously, a sharp market correction may cause your collateral value to breach the required margin maintenance threshold. In such events, the lender issues a margin call requiring you to pledge additional securities or deposit cash. If you fail to meet the margin call within the stipulated timeframe, the lender will unilaterally liquidate your pledged units in the open market to recover their funds.
Key Factors to Evaluate Before Taking a Loan
- Total Cost of Borrowing: Look beyond the monthly EMI; calculate the total cumulative interest, upfront fees, taxes, and total repayment amount over the entire loan tenure.
- Interest Rate Benchmark: Clarify whether the rate is fixed or floating, the underlying benchmark index, the reset frequency, and whether interest is calculated on a daily reducing balance or flat rate basis.
- Key Facts Statement (KFS): Under RBI mandates, regulated lenders must provide a standardized Key Facts Statement (KFS) clearly stating the Annual Percentage Rate (APR), detailed breakup of all fees/charges, and recovery policies before executing the loan agreement.
- Prepayment & Foreclosure Terms: Review lock-in periods, part-payment terms, and foreclosure charges.
- Debt Affordability: Ensure your total monthly debt servicing across all loans remains well within manageable limits (ideally below 35%–40% of net monthly take-home pay) without impairing your essential emergency savings.
Provide accurate and complete information regarding income, existing liabilities, and collateral on all loan applications. Review loan agreements and fee schedules thoroughly before signing, and consult an independent financial advisor when planning significant long-term commitments.
This article is for informational and educational purposes only and does not constitute credit, legal, or financial advice. Loan eligibility, interest rates, and approval terms are subject to individual lender policies and regulatory frameworks.